


The Illusion of the "Silicon Savannah" Successor: Why Rwanda’s IT Sector is Dead in the Water
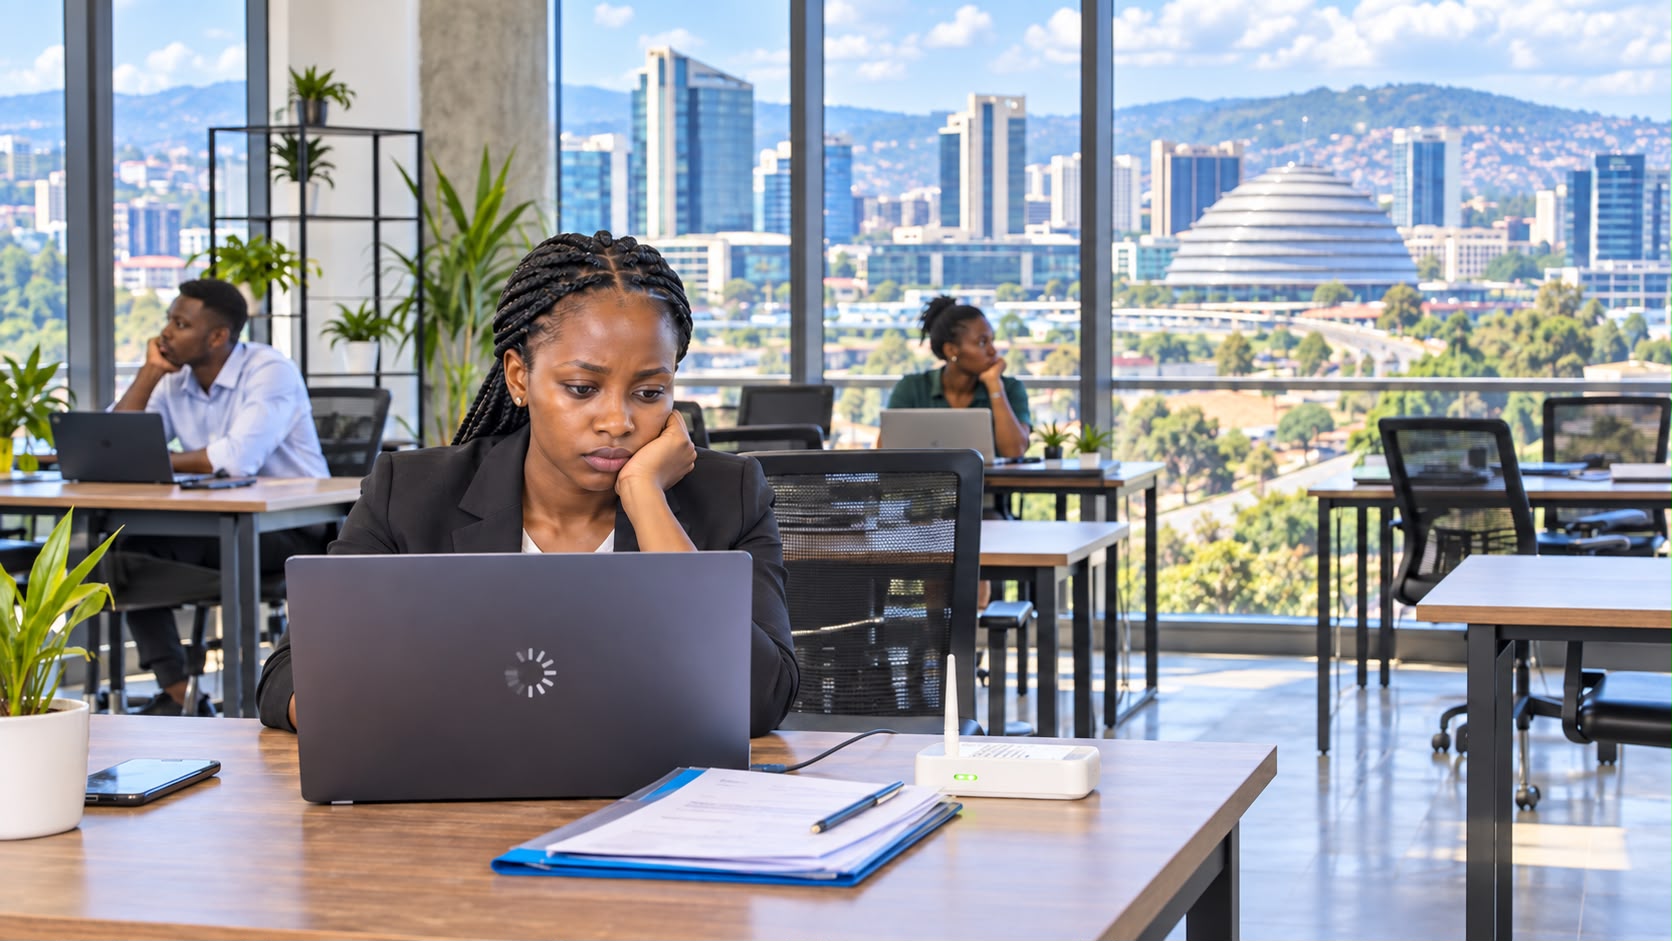
For over a decade, international tech conferences, glossy economic reports, and PR campaigns have sold a glittering narrative: Kigali is transitioning from a post-conflict society into the "Singapore of Africa." We are told of automated cashless buses, high-speed fiber optics, and ambitious tech cities.
But if you peel back the slick marketing layers and look at the brutal economic realities on the ground, the narrative collapses. Rwanda's tech revolution isn't just stalled—it is practically dead in the water.
A tech ecosystem cannot survive on PR alone. To see just how far behind Rwanda has fallen, one only needs to look across the border to Kenya. While Rwanda has attempted a highly controlled, artificial, top-down digitization plan, Kenya has built an unstoppable, bottom-up digital empire.
Behind the facade of Kigali's hyper-modern digital economy lies an ecosystem choked by non-existent job markets, a broken higher education pipeline, and an economy so heavily monopolized by the ruling party that independent private innovation is effectively impossible. Here is the unvarnished truth about why Rwanda’s IT sector is failing to launch, contrasted against the soaring reality of Kenya’s "Silicon Savannah."
1. The Microscopic Job Market vs. Kenya's Employment Engine
The first, and most damning, metric of failure is the sheer absence of actual employment in Rwanda.
According to national labor force data, out of Rwanda’s 4.7 million workforce, the Information and Communications Technology (ICT) sector employs a grand total of roughly 19,000 people. That equates to an absolute microscopic 0.4% of total employment.
A tech sector cannot be an economic driver if it only accommodates a tiny handful of elite professionals in a single pocket of Kigali. Graduating with an IT degree in Rwanda is statistically a fast track to underemployment.
Contrast this with Kenya. Kenya's digital economy is a massive, self-sustaining employment powerhouse. The ICT sector directly and indirectly supports hundreds of thousands of jobs across the country. It is powered by a massive ecosystem of over 300,000 active developers, digital gig workers, tech consultants, and corporate engineers. In Nairobi, tech is not a niche government experiment; it is a mainstream pillar of survival and wealth creation for an entire generation of youth.
2. Dysfunctional Universities Producing "Semi-Illiterate" Tech Graduates
The second pillar of failure is the academic institutions responsible for fueling the ecosystem. Local tech managers and foreign companies setting up operations in Kigali routinely whisper an uncomfortable truth: traditional Rwandan universities are profoundly broken.
The public university system—anchored by the University of Rwanda—consistently ranks dead last compared to regional powerhouses. The issues run deep:
• Severe Practical Deficits: Curricula remain rigidly theoretical. Students graduate knowing how to pass written exams about coding paradigms without ever having pushed production-ready code to a live server.
• The Communication Chasm: The abrupt historical pivot from French to English instruction left systemic language gaps. A significant portion of tech graduates struggle to communicate complex technical requirements in fluent professional English, leaving them functionally "semi-illiterate" when dealing with global clients.
Now, look at the institutional engine driving Kenya. Nairobi’s success is anchored by a matrix of world-class universities that pump out industry-ready professionals annually. Public giants like Jomo Kenyatta University of Agriculture and Technology (JKUAT) and the University of Nairobi produce elite engineering talent deeply grounded in practical mathematics and software design.
Meanwhile, premium private institutions like Strathmore University maintain aggressive partnerships with global tech firms, constantly updating their curricula to include advanced data science, cybersecurity, and cloud architecture. Kenyan graduates do not just know about code—they build scalable production software the day they graduate, and they communicate flawlessly on the global stage.
3. The Digital Pipeline: Internet Costs and the Reality of Speed
A glaring metric where Rwanda’s PR actively clashes with reality is basic digital infrastructure. Kigali frequently boasts about its nationwide fiber-optic cables, but for the actual software engineer trying to push code, deploy cloud instances, or jump on international client calls, the everyday reality is incredibly restrictive.
Kenya's digital pipeline is anchored by direct subsea fiber-optic cables landing in Mombasa, fostering an aggressively competitive telecom market (Safaricom, Airtel, Jamii Telecom). This competition drives costs down and bandwidth up. Landlocked Rwanda, by contrast, relies on transit routes through neighboring countries to access these undersea cables, which significantly inflates wholesale bandwidth prices.
The data reflects a massive regional divide:
• Internet Costs: In Nairobi, uncapped, high-speed fiber-to-the-home (FTTH) packages are affordable and accessible to middle-class households and bootstrapping developers. In Kigali, reliable high-speed fixed broadband remains an expensive luxury, often costing nearly double the price per megabit compared to Kenya. For a junior developer, data caps and high costs are a constant friction point.
• Connectivity Speeds: While mobile speeds fluctuate, Kenya's fixed broadband infrastructure consistently outpaces Rwanda's. Nairobi's average fixed download and upload speeds are significantly faster and feature far lower latency to European and American servers.
Developers who have attempted to work out of both markets express deep frustration with Kigali's bottlenecked reality.
"In Nairobi, I took seamless 100Mbps fiber for granted," shares a senior full-stack developer who spent six months trying to freelance out of Kigali. "When I moved to Kigali, I spent half my time managing data budgets and dealing with frustrating micro-drops in connectivity. You cannot build a modern DevOps pipeline or work comfortably on international remote teams when basic uncapped fiber costs a premium and still acts up when it rains. Kigali looks pretty, but Nairobi’s internet has actual teeth."
Another software architect working for a regional logistics platform adds:
"Kigali is great for an executive who just needs to check emails and read slide decks. But if you are downloading massive Docker images, pushing heavy builds to AWS, or running intensive testing environments, the infrastructure just isn't there at a reasonable price point. The cost-to-speed ratio in Rwanda is a massive penalty on independent innovation."
4. M-Pesa and the Startup Funding Chasm
Rwanda's tech landscape lacks a foundational layer of infrastructure that everyday citizens actually use to transact. Kenya, on the other hand, is home to M-Pesa, the undisputed crown jewel of global fintech.
Launched by Safaricom, M-Pesa completely bypassed legacy brick-and-mortar banking, driving Kenya’s financial inclusion rate to an astonishing 84%+. But M-Pesa’s greatest gift to the Kenyan IT sector wasn't just mobile wallets—it was Safaricom’s decision to open up its APIs to independent software developers.
Because any young programmer in Nairobi can seamlessly integrate M-Pesa payments into an application, Kenya sparked a massive explosion of organic tech startups across agritech (Twiga Foods), healthtech, and e-commerce.
This vibrant startup ecosystem has turned Kenya into a venture capital magnet. Kenya routinely captures hundreds of millions of dollars in VC funding annually—frequently accounting for over 30% to 40% of all startup capital entering the entire African continent. Rwanda’s total annual venture capital footprint, by comparison, is an insignificant rounding error.
5. Multinationals vs. The Chokehold of Crystal Ventures
The final nail in the coffin for Rwanda’s independent IT dream is the structural reality of its private sector. In Kenya, the market is a magnet for the world's largest foreign technology multinationals. Companies like Google, Microsoft, Amazon Web Services (AWS), and Visa have not just opened small administrative outposts in Nairobi—they have established massive regional engineering headquarters, such as Microsoft’s multi-million dollar African Development Centre (ADC).
These foreign giants bring immense value: they inject cutting-edge tech infrastructure, introduce global best practices, and train local Kenyan engineers at the absolute highest standards. When these engineers eventually leave these corporate giants, they go on to launch their own heavily funded, highly sophisticated local startups. The market is aggressively competitive, decentralized, and entirely uncaptured.
In Rwanda, this kind of open-market, multinational-driven ecosystem is impossible. The entire domestic private sector is heavily distorted and captured by the ruling party’s massive business empire: Crystal Ventures Ltd (CVL).
Originally founded as Tri-Star Investments, Crystal Ventures is a multi-million-dollar ruling party conglomerate that exerts a near-monopoly over the country's most lucrative sectors. It dominates consumer goods, construction, aviation, and critically, technology infrastructure via massive ownership stakes in entities like MTN Rwanda.
This party-owned corporate structure creates a lethal dynamic for independent IT innovation:
• Crowding Out Competition: Independent tech startups cannot fairly compete for lucrative municipal or state digitization contracts. The premium deals almost invariably flow into the ecosystem of companies tied directly to CVL or the military.
• Investor Reluctance: Savvy international venture capitalists quickly realize that entering the Rwandan market means navigating an economy where the lines between the regulator (the state) and the primary commercial competitor (the ruling party) are completely blurred. They take their millions to Nairobi instead.
• Talent Monopolization: The few high-paying, secure engineering jobs that do exist are heavily clustered around these party-affiliated institutions, starving small, independent software shops of top-tier local minds.
Conclusion: The House of Cards
Rwanda’s IT dream is effectively a carefully constructed PR campaign built on a foundation of sand. You cannot build a "Silicon Savannah" successor when your universities turn out functionally unready graduates, your internet speeds lag behind at inflated costs, your market only yields 19,000 sector jobs, and your commercial tech landscape is suffocated by a ruling-party corporate monopoly.
While Kenya dominates the continent through the raw power of open competition, massive university pipelines, multinational tech injection, and world-shifting innovations like M-Pesa, Rwanda remains trapped in a stagnant, top-down illusion. Until the state dismantles the commercial monopolies of Crystal Ventures and allows a genuine, independent, bottom-up private sector to breathe, Rwanda’s tech sector will remain exactly what it is today: dead in the water.
No comments yet. Be the first to comment.